An ₹85-lakh annual package sounds like the dream number a person worked and studied hard for. Let’s agree that it’s the kind of number that can make a job offer difficult to refuse. For a professional with more than a decade of experience, an IIT Roorkee degree, an ISB MBA and a senior corporate role, it might seem like the natural payoff. But what if the ₹85 lakh mentioned on the offer letter does not mean ₹85 lakh in your bank account?That is the exact question Sidharth Maheshwari, an AVP with 12-plus years of experience, IIT Roorkee and ISB credentials, has put before professionals through a detailed Instagram post. In his post, Maheshwari has shared the actual CTC-reality that has left people shocked. The 36-year old man describes himself as AVP at a private firm.His post starts with a number many job seekers would immediately notice: ₹85,00,000.But when he breaks it down, you’ll be shocked:According to the offer structure he shared, the ₹85 lakh CTC consisted
- ₹52 lakh in fixed compensation
- ₹13 lakh in variable pay
- ₹15 lakh in ESOPs
- ₹5 lakh joining bonus
The fixed component itself included:
- ₹20 lakh basic salary
- ₹10 lakh HRA
- ₹18.64 lakh special allowance
- ₹2.4 lakh employer PF
- ₹0.96 lakh gratuity
On paper, all the abovementioned figures add up to an impressive ₹85 lakh. But Maheshwari’s point is that CTC and take-home salary are two different things.The ₹85 lakh that is not ₹85 lakh, how?The first major difference he points out is between money included in the company’s cost to employ someone and money that actually becomes part of the employee’s regular cash compensation.As per his calculation, ₹2.4 lakh of employer PF and ₹0.96 lakh of gratuity (₹3.36 lakh) are part of the stated CTC but are not money that actually he receives in his monthly bank account.Now this brings down his regular payroll figure to ₹48.64 lakh.Why such distinction?Employees need to understand the reason behind this distinction.Employer PF is a retirement benefit rather than monthly spendable income. EPFO’s official contribution framework also provides for employer and employee contributions to provident fund (subject to the applicable rules).Income tax, the main deductionHe further calculates ₹2.4 lakh towards employee PF and around ₹10.57 lakh in income tax under the new tax regime. It leaves approximately ₹35.6 lakh as annual net salary which means only around ₹2.97 lakh per month! Shocking, right?The number people noticed intentionally was 85 but after all the deductions, the value is now just 2.97. A huge drop. That’s not even ₹5 lakh a month.Then there is variable payThe ₹13 lakh variable component is another important part.This is something which is not a part of a fixed salary as variable compensation can depend on company or individual performance (depends). Maheshwari illustrates this by assuming an 80% payout, which would mean ₹10.4 lakh before tax rather than the full ₹13 lakh.He also points out that variable pay may arrive annually rather than being distributed equally across 12 months. For someone planning monthly expenses, EMIs, rent or investments, it matters.A salary of ₹2.97 lakh every month is fundamentally different from receiving a potentially larger amount once a year, depending on performance.₹15 lakh ESOPs but not ₹15 lakh in cash
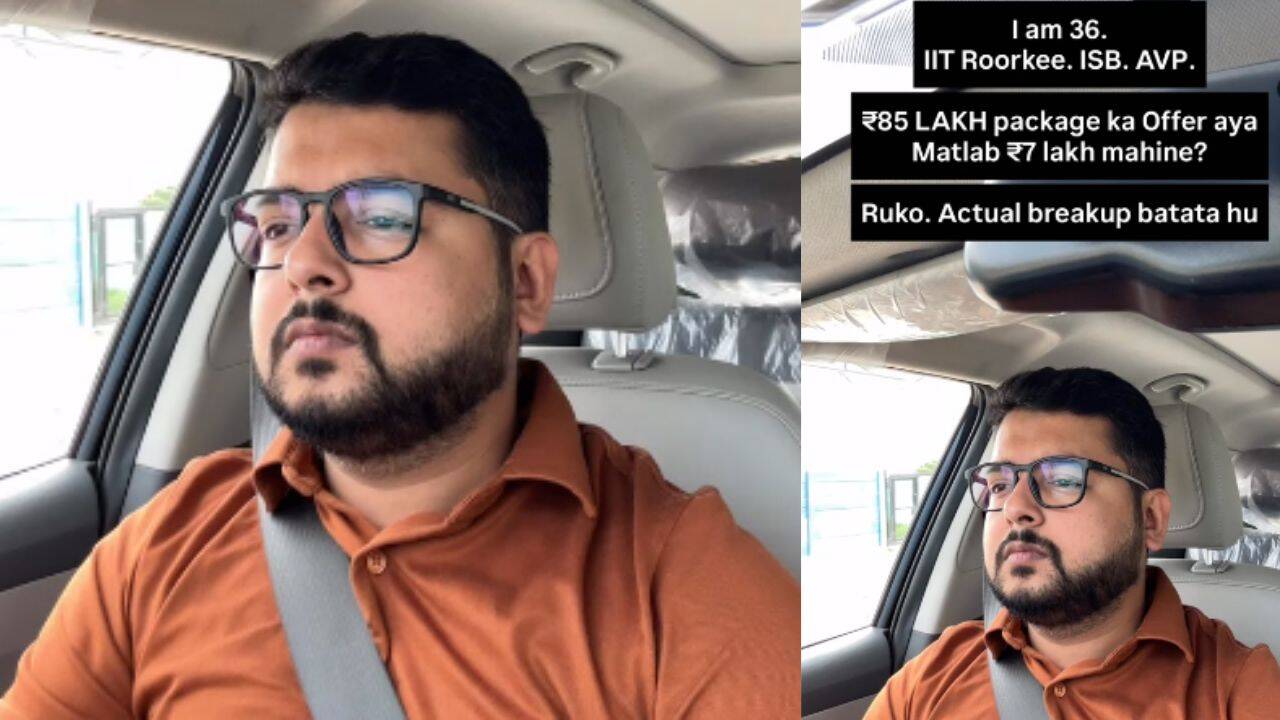
Sidharth Maheshwari (Instagram)
Now comes the part of the package that can sound attractive on an offer letter: ₹15 lakh in ESOPs.Maheshwari says the ESOP component in his example vests over four years, with a one-year cliff. That means the stated value should not automatically be treated as ₹15 lakh of current income.An employee may have to remain with the company for the shares or options to vest according to the plan’s terms, and the eventual value can depend on the company’s valuation, liquidity and the terms governing the ESOPs.The joining bonus also has a catchThe ₹5 lakh joining bonus is subject to tax cut. It reduces the amount actually received. He also notes a clawback condition in his example: leaving before 12 months could require the employee to return the bonus.Why people can connect with his postThe larger element of Maheshwari’s post is not really about whether ₹85 lakh is a good or bad package. It is about how people psychologically process salary numbers.For a 25 or 28 year old, this can feel transformative. But as responsibilities grow, the question may change from “What is the CTC?” to “How much of it is guaranteed, and how much will I actually receive?”He writes that if he were 28, he might have accepted an ₹85-lakh number immediately. At 36, however, he says his first question would be different: “Fixed kitna hai?”Because sometimes, the most important number in a ₹85-lakh offer letter is not ₹85 lakh at all. It is the amount that lands in your account every month.